A startup's valuation is not a fact. It is a number two sides agree on. It depends on your stage, your traction, and what similar companies are raising right now. Early-stage companies get valued on team and story. Later-stage companies get valued on revenue and growth.
Startup valuation methods should match where you are. Using a discounted cash flow model when you have zero revenue is a waste of time. Using a simple scorecard when you have $10M ARR is leaving money on the table. This guide breaks down the methods that actually show up in real term sheets. Comparables, Scorecard, Berkus, Venture capital method and more. Read on and learn how to value what you are building.
Why Startup Valuation Is Different?
Traditional valuation assumes a company will keep operating and generating predictable cash. Startups do not have that luxury. Most are losing money. Many will fail. Their financials are guesses stacked on guesses .
That is why standard tools like DCF often fall apart at the early stage. The inputs are too uncertain. Investors know this. They price the risk into the valuation. Fewer unknowns mean a higher number .
Read More: How Startup Funding Rounds Work: A Simple Guide
The Main Startup Valuation Methods
Comparable Transactions
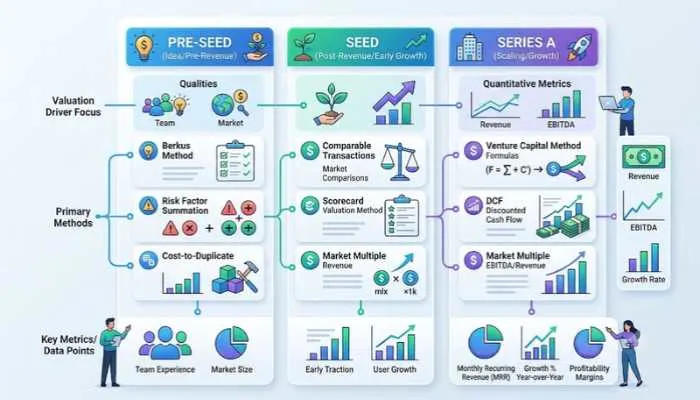
This is the quiet default behind almost every early deal. Investors look at what similar startups raised at your stage and adjust for your traction . If three pre-seed SaaS companies in your region raised at $4M, you negotiate inside that band unless you have a reason to break out.
Scorecard Method
Common for pre-revenue companies. It starts with the average valuation of recent deals in your region. Then it adjusts up or down based on team, market size, product, competition, and sales channels . The weights are usually 30% team, 25% opportunity, and smaller percentages for the rest.
Berkus Method
This assigns a fixed dollar value to milestones. A sound idea. A prototype. A quality team. Early traction. Strategic relationships. Each element gets a value, often capped at a few hundred thousand dollars . It is useful when there is no revenue to anchor on. The total gives you a rough pre-money number.
Venture Capital Method
This works backward. You estimate what the company could sell for in five to eight years. You apply a target return multiple (often 10x or more for early-stage). Then you discount that back to today .
The formula is simple. Post-money valuation equals terminal value divided by anticipated ROI. Pre-money is post-money minus the investment .
Discounted Cash Flow
This is the standard in finance. It projects future cash flows and discounts them to present value. For early startups, it is mostly noise. The projections are too uncertain. It matters more once revenue is predictable, closer to Series A . Even then, it is usually blended with comparables.
First Chicago Method
This handles the "small chance of becoming huge" problem. You build three scenarios: worst case, normal case, and best case. You value each one. Then you assign a probability to each. The weighted average is your valuation . It is meant for post-revenue startups.
How to Calculate Valuation Based on Funding?
There is a simple relationship between the amount you raise and the valuation. Founders usually sell 15% to 25% per round .
If you raise $2M and give away 20% of the company, the post-money valuation is $10M. The pre-money is $8M. That is the math investors will run in their heads.
The previous funding round method is even simpler. Take the pre-money multiple from your last round. Multiply it by the total capital raised to date. That gives you a pre-money valuation for the new round . This is a static method. It does not account for new developments. But it is a starting point.
Startup Acquisition Valuation Methods
When a larger company buys a startup, the math changes. Buyers look at strategic value. What does this acquisition give us that we cannot build ourselves?
Common methods include comparable company analysis, precedent transactions, and revenue multiples (EV/Revenue or EV/ARR). For profitable targets, EV/EBITDA is used. Earnouts are common. The buyer pays part upfront and part when the startup hits certain milestones .
The key difference from fundraising valuation is control. A buyer is paying for the whole company, not a minority stake. That usually commands a premium.
You May Also Read: How Startups Get Seed Funding: A Practical Guide
Startup Valuation Calculator
You can run a quick estimate yourself. Free tools like SaaStr's valuation calculator or Eqvista's business valuation tool take your ARR, growth rate, and other inputs and return a range based on current comps .
But treat the output as a starting point, not a final answer. A calculator cannot see your team, your market, or your negotiation leverage. It gives you gravity. You still have to negotiate.
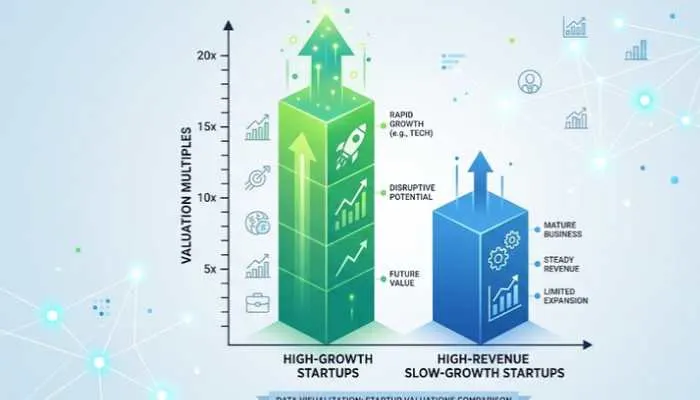
One thing the data shows: growth rate matters more than ARR. A $5M ARR company growing 200% year over year is worth more than a $20M ARR company growing 30% . Founders anchor too much on the revenue number. The growth rate is what investors are buying.
FAQs
1. What are the main startup valuation methods?
The main ones are comparable transactions, scorecard, Berkus, venture capital method, discounted cash flow, and First Chicago. Most early rounds blend two or three rather than relying on one .
2. How do I calculate startup valuation based on funding?
If you raise $2M for 20% equity, the post-money is $10M and pre-money is $8M. Founders typically sell 15% to 25% per round. The raise amount and valuation are linked .
3. What is the Berkus method?
It assigns a fixed dollar value to milestones like a sound idea, prototype, quality team, and early traction. Each element gets a value, often capped at a few hundred thousand dollars. The total gives a rough pre-money number .
4. What is the venture capital method?
It works backward from a projected exit value. You estimate the terminal value, apply a target return multiple, and discount back to today. It is common for seed-stage deals .
5. What are startup acquisition valuation methods?
Buyers use comparable company analysis, precedent transactions, and revenue multiples like EV/Revenue or EV/ARR. Earnouts are common. Acquisition valuations include a control premium because the buyer is purchasing the whole company .
6. Are startup valuation calculators accurate?
They give a range based on comps. They are useful for grounding your expectations. But they cannot see your team, market, or negotiation leverage. Treat the output as a starting point, not a final answer .
7. Why is DCF bad for early startups?
The projections are guesses. Traditional DCF assumes predictable cash flows and a going concern. Early startups have neither. It becomes more useful closer to Series A when revenue is predictable .
8. What matters more, ARR or growth rate?
Growth rate. A $5M ARR company growing 200% is worth more than a $20M ARR company growing 30%. Founders anchor too much on the revenue number. Investors are buying the future growth .